
GSTR-3B Filing Guide 2026: Due Date, Late Fee, Tax Payment & Common Errors
GSTR-3B Filing Guide 2026: Due Date, Late Fee, Tax Payment & Common Errors
A practical guide for businesses, accountants and GST professionals to prepare GSTR-3B, review liability, reconcile ITC, pay tax and avoid costly return-filing mistakes.
Quick Answer: What Is GSTR-3B?
GSTR-3B is a summary GST return in which eligible taxpayers declare outward supplies, inward supplies liable to reverse charge, eligible input tax credit, tax liability and tax payment for a tax period. Before filing, reconcile sales with GSTR-1, review eligible ITC using GSTR-2B and purchase records, calculate net tax payable, and ensure sufficient cash or credit balance is available in the relevant electronic ledgers.
Important: Due dates, late-fee rules, interest provisions, filing frequency, QRMP applicability, return tables and GST portal processes can change. Always confirm the applicable due date, filing requirement and payable amount on the official GST portal or with a qualified GST professional before filing.
What Is GSTR-3B and Why Is It Important?
GSTR-3B is a summary self-declaration return used by taxpayers to report GST liability and discharge tax dues for the relevant tax period. It is not simply a formality: the amounts reported in GSTR-3B should be supported by your sales records, GSTR-1 data, purchase register, GSTR-2B data, reverse-charge transactions and available ITC.
A correct GSTR-3B filing workflow helps you identify tax payable, use eligible input tax credit responsibly, plan cash payments and maintain stronger GST compliance records for future reconciliations and annual return preparation.
Monthly GSTR-3B Compliance Workflow
GSTR-3B Due Date: What Should You Check?
The GSTR-3B due date can depend on whether you file monthly or quarterly under QRMP, the applicable state or Union Territory group, your GST registration category and any extension or notification issued for the period. Do not rely only on an old calendar screenshot or a generic social-media post.
Before You Mark a Due Date, Verify:
- Whether your GSTIN files GSTR-3B monthly or under the QRMP scheme.
- The correct financial year and tax period selected on the GST portal.
- Whether your state or Union Territory falls in a specific QRMP due-date group.
- Whether any extension, waiver or GST portal advisory applies to the period.
- Whether you have pending earlier returns that may affect your compliance status.
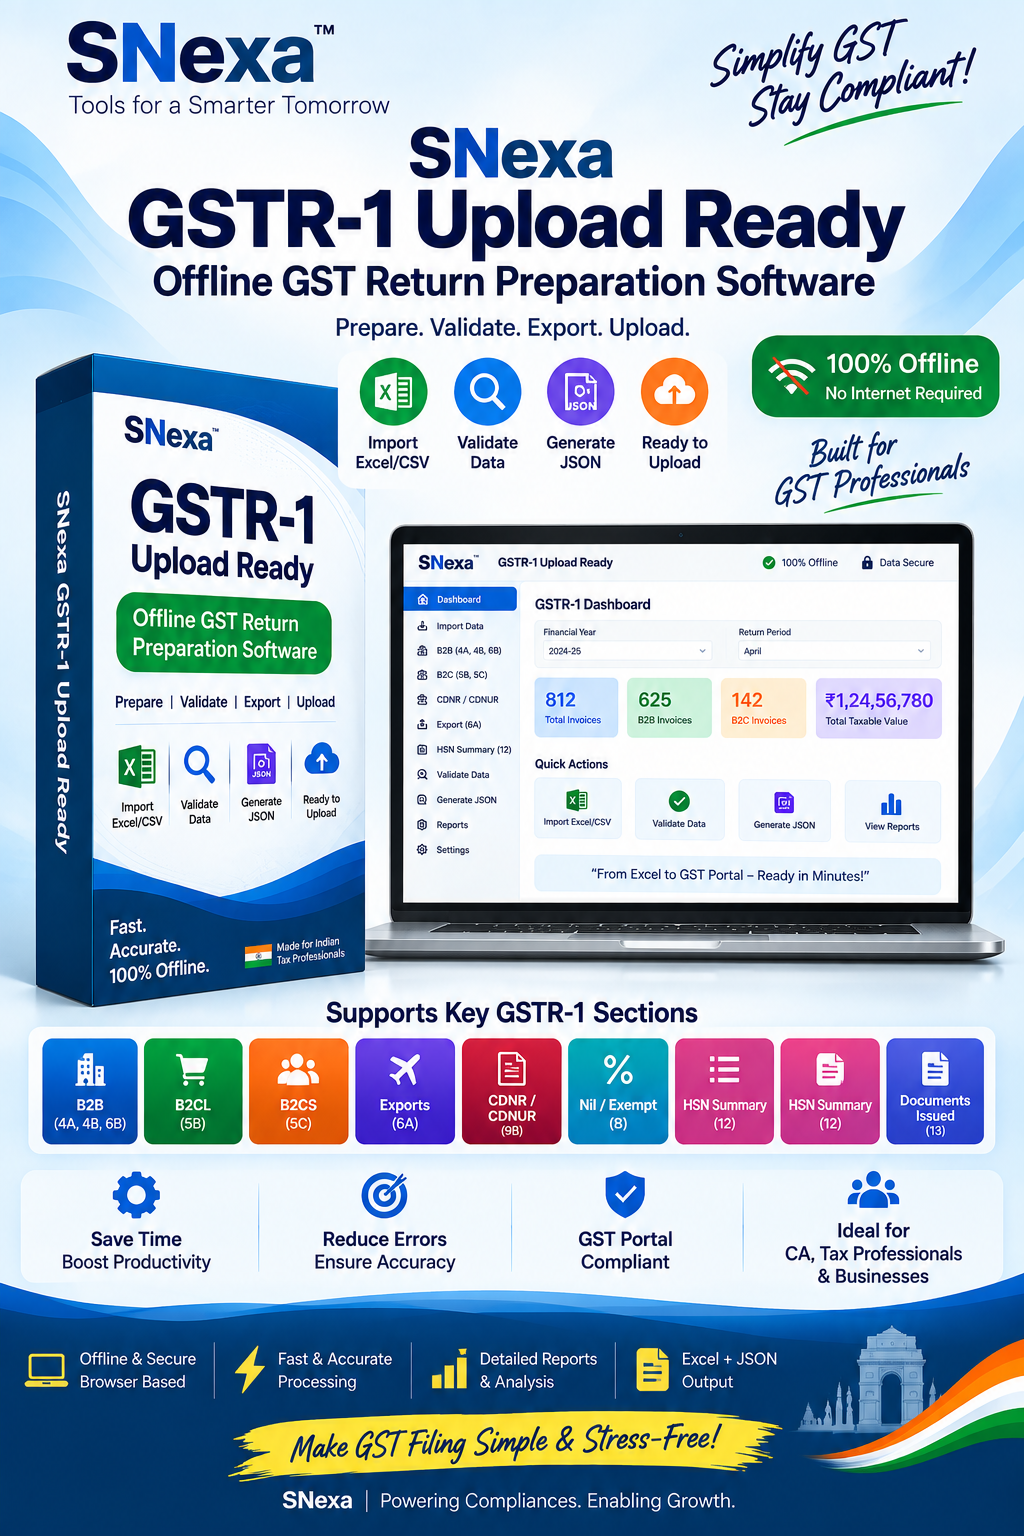
Prepare GSTR-1 Data Before You Finalize GSTR-3B
Your GSTR-3B outward taxable-supply figures should be reviewed against your GSTR-1 sales data. Snexa GSTR-1 Upload-Ready Tool helps organize outward supply details and prepare an upload-ready JSON workflow before you move to GSTR-3B review.
Explore Snexa GSTR-1 Tool →How to Prepare GSTR-3B Step by Step
Use this practical pre-filing checklist before entering final figures on the GST portal.
Prepare your taxable sales, exempt supplies, nil-rated supplies, non-GST supplies, export information, credit notes and debit notes for the relevant tax period.
Compare outward supply figures with your GSTR-1 working, sales register, e-invoice data where applicable, marketplace sales reports and customer invoices.
Check purchase invoices, supplier GSTINs, invoice dates, taxable values, taxes, reverse-charge items, blocked credits and any ITC reversals or reclaims before deciding the eligible ITC amount.
Calculate tax liability separately under IGST, CGST, SGST or UTGST and cess, based on the nature of supplies and applicable tax rates.
Identify inward supplies on which tax is payable under reverse charge and ensure the related liability is considered as applicable.
Review available electronic credit-ledger balances and calculate the remaining amount that needs to be paid through the electronic cash ledger. Interest, penalty and late fee generally require cash payment.
Review all populated values, complete the applicable tax-payment process, submit GSTR-3B through the GST portal and save the acknowledgement and working papers for your records.

Reconcile GSTR-2B with Your Purchase Register Before Claiming ITC
Input tax credit can affect your GSTR-3B tax payable amount. Snexa ITCSafe helps you compare GSTR-2B or GSTR-2A data with purchase records, identify missing invoices, GSTIN mismatches, tax mismatches and records that need review before GSTR-3B filing.
Explore Snexa ITCSafe →GSTR-3B Tax Liability: What Should Be Reviewed?
| Area to Review | Examples | Why It Matters |
|---|---|---|
| Outward taxable supplies | B2B, B2C, export, e-commerce, debit notes and amendments. | Forms the basis of output GST liability and should align with records and GSTR-1 working. |
| Exempt / nil-rated / non-GST supplies | Exempt turnover, nil-rated goods, non-GST transactions. | Ensures total turnover reporting is complete and correctly classified. |
| Reverse-charge transactions | Applicable notified inward supplies, import-related or other RCM items. | RCM liability may require separate reporting and payment treatment. |
| Eligible ITC | GSTR-2B matched invoices, eligible expenses and permitted credits. | Reduces net tax payable only when correctly reviewed and eligible. |
| ITC reversals / ineligible ITC | Blocked credits, non-business use, unpaid-vendor rules and reversals where applicable. | Helps prevent excess ITC claims and later disputes. |
| Cash and credit ledger balances | Available IGST, CGST, SGST or UTGST credit and cash balances. | Determines whether additional cash needs to be deposited before filing. |
GSTR-3B Late Fee and Interest: Key Points to Know
Delayed GSTR-3B filing can result in late fee, while delayed payment of tax may also result in interest. The amount can depend on whether the return is nil or regular, how many days have passed, current rate notifications, maximum caps, tax liability and the portal’s final computation.
Late fee and interest should not be treated as the same thing. A taxpayer may face late fee because a return was filed after the due date, while interest can arise because tax payment was delayed. Review the final amount shown on the GST portal before making payment.
Before Paying Any Late Fee or Interest, Check:
- Whether the return is a nil return or contains taxable supplies.
- The actual due date applicable to your filing category and state.
- The filing date and the number of delayed days.
- Any government-notified waiver, extension or maximum late-fee cap.
- Tax, interest and fee amounts displayed on the GST portal before final filing.
10 Common GSTR-3B Filing Errors to Avoid
Your bank receipt may exclude returns, discounts, marketplace fees, TCS or other adjustments. Use actual invoice and sales records.
Outward-supply figures should be reviewed against GSTR-1 working before final filing.
Review GSTR-2B, purchase register, supplier invoices and ITC eligibility before claiming credit.
Identify applicable RCM transactions and account for them correctly.
Review IGST, CGST, SGST or UTGST and cess values before submitting the return.
Returns, post-sale discounts and corrections may require a proper credit-note or amendment review.
Complete reporting requires correct classification of taxable and non-taxable outward supplies.
Check if sufficient electronic cash balance is available after eligible ITC use.
Last-day filing may leave little time to correct portal, payment or document issues.
Keep sales reports, ITC workings, reconciliations, payment records and filed-return acknowledgement safely.
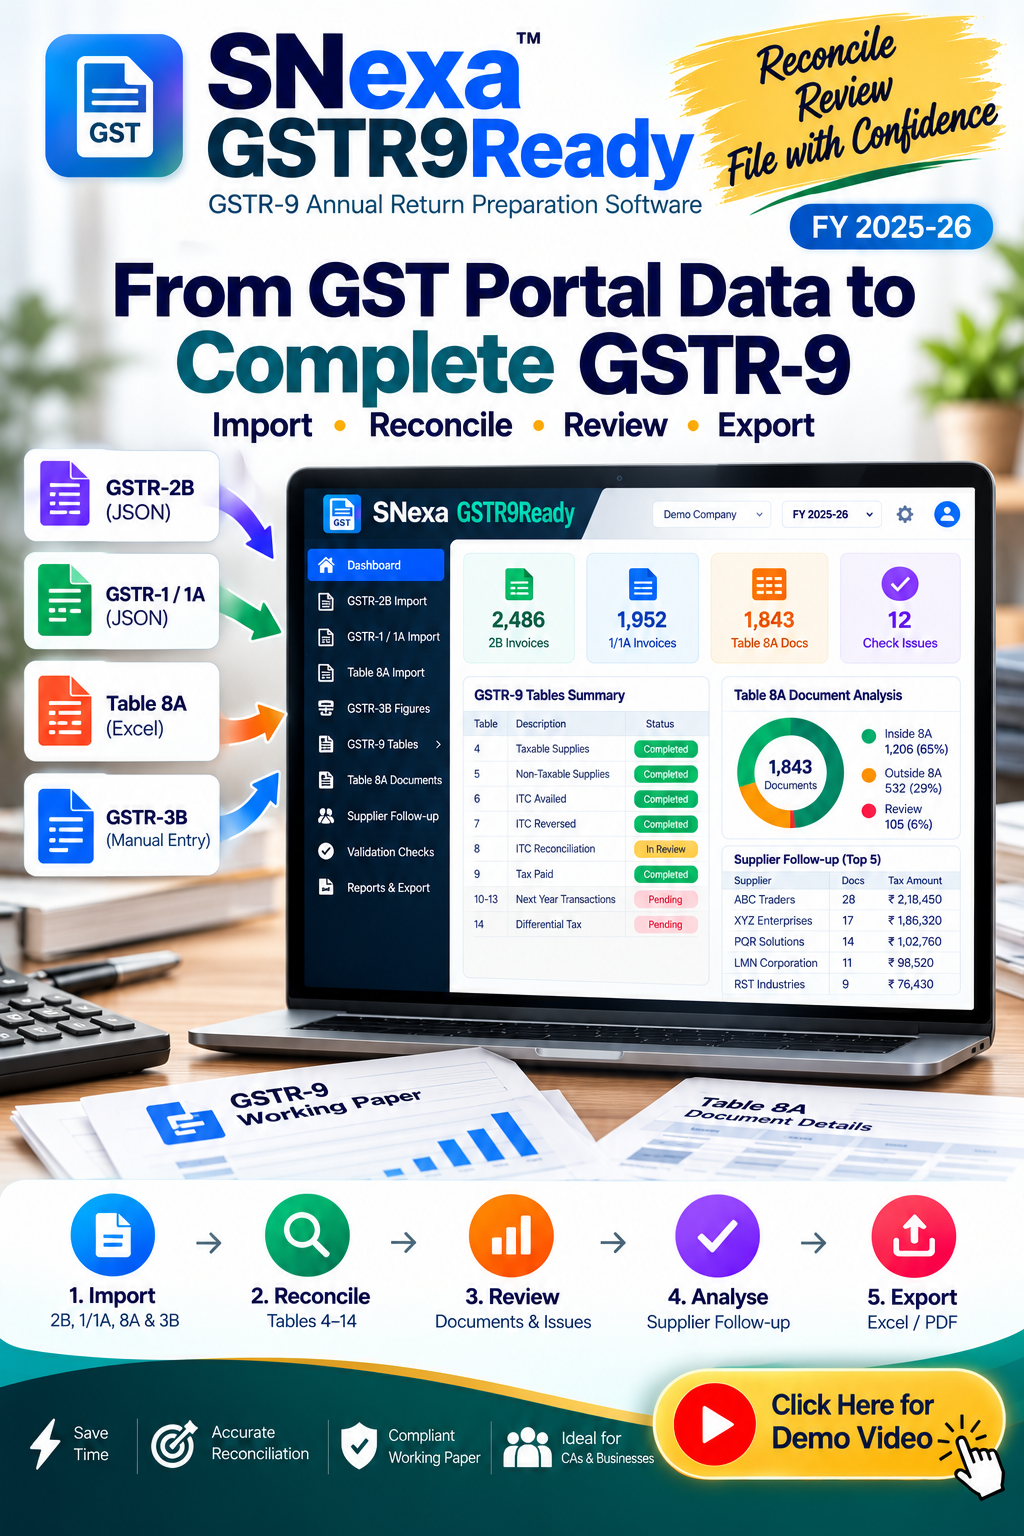
Your Monthly GSTR-3B Records Build Your GSTR-9 Foundation
Regular review of GSTR-1, GSTR-3B, purchase records and ITC helps reduce year-end reconciliation pressure. Snexa GSTR9Ready is designed to support annual GSTR-9 preparation and reconciliation for Financial Year 2025–26.
Explore Snexa GSTR9Ready →GSTR-3B Filing Checklist
Sales and Liability
✓ Sales register reviewed
✓ GSTR-1 working checked
✓ Credit/debit notes reviewed
✓ Exempt and nil-rated supplies classified
✓ RCM transactions checked
Input Tax Credit
✓ GSTR-2B downloaded
✓ Purchase register reconciled
✓ Missing invoices identified
✓ Ineligible ITC reviewed
✓ Reversal or reclaim entries checked
Payment and Records
✓ Cash and credit ledger reviewed
✓ Cash requirement planned
✓ Due date verified
✓ Final portal figures checked
✓ Acknowledgement and workings saved

Need a Complete GST Workflow Instead of Separate Spreadsheets?
Manage sales return preparation, ITC reconciliation, compliance planning and annual return working with a more organized toolkit approach. Snexa GST Toolkit is designed for businesses, accountants and GST professionals who want multiple GST compliance utilities in one package.
Explore Snexa GST Toolkit →Frequently Asked Questions About GSTR-3B
What is GSTR-3B?
GSTR-3B is a summary GST return used to declare tax liability and discharge GST dues for the applicable tax period. It requires a careful review of sales, reverse-charge transactions, input tax credit and tax payment information.
What should be checked before filing GSTR-3B?
Review GSTR-1 sales data, sales register, GSTR-2B, purchase register, eligible ITC, reverse-charge liabilities, exempt supplies, credit notes, debit notes, electronic cash ledger and electronic credit ledger before filing.
Can I claim all ITC shown in GSTR-2B?
Not automatically. GSTR-2B is an important reference for ITC review, but eligibility depends on applicable GST conditions, business purpose, valid documentation, tax payment conditions, blocked-credit rules and other requirements. Reconcile GSTR-2B with books and consult a GST professional when needed.
What happens if GSTR-3B is filed late?
Late filing can result in late fee. Delayed tax payment may also result in interest. The applicable amount can depend on the return type, delay period, tax liability and current rules, so check the GST portal calculation before payment.
Why should I compare GSTR-1 and GSTR-3B?
GSTR-1 reports outward supply details, while GSTR-3B reports summary liability and payment. Comparing them helps identify differences in sales, credit notes, amendments, taxes and reporting classification before the records become harder to reconcile later.
Build a Better GST Filing Workflow
Prepare outward supplies, review GSTR-2B input tax credit, maintain reconciliation records and plan annual GST compliance with Snexa’s focused GST tools.
View Snexa GST Toolkit →Disclaimer: This article is for general educational purposes only and does not constitute tax, legal or accounting advice. GST return formats, due dates, late-fee rules, interest calculations, ITC conditions, GST portal fields, notifications and filing procedures may change. Always verify the latest requirements on the official GST portal and consult a qualified GST professional before filing or making tax payments.


